-
Technology
-
Industry
-
Solutions
-
- ASSET MANAGEMENT
- CUSTOMER EXPERIENCE MANAGEMENT
- CYBER SECURITY
- DATA CENTER
- DOCUMENT MANAGEMENT
- ELECTRONIC DATA INTERCHANGE
- ENTERPRISE DATA MANAGEMENT
- ENTERPRISE RESOURCE PLANNING
- ENTERPRISE RISK MANAGEMENT
- ENTERPRISE-GRADE WEB DATA SOLUTIONS
- FACILITY MANAGEMENT
- FIELD SERVICE
- IDENTITY AND ACCESS MANAGEMENT
- INFRASTRUCTURE
- IT SERVICE MANAGEMENT
- MANAGED IT SERVICES
- PAYMENT AND CARD
- PROJECT MANAGEMENT
- SOFTWARE TESTING
- STORAGE
- VIDEO SOLUTIONS
- WORKFLOW
-
-
Platforms
-
Functions
- Leadership Perspectives
- Innovation Insights
- Research
- Magazines
- News
- CXO Awards


Contributory Virtus Investment Partners on the invitation from our Editorial

Raiz Federal Credit Union
Amy Krasikov, Vice President of Digital ExperienceEliminating Friction in Digital Banking: Lessons From a Successful Transformation
Amy Krasikov, Vice President of Digital Experience
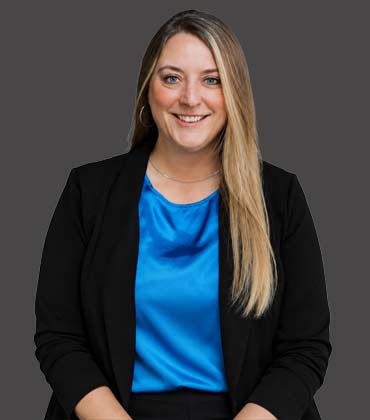
Amy Krasikov
Have you ever tried to open an account online and thought, “What is this? Why is this taking so long?” That is exactly how I felt going through our online account opening experience. Then, I received a call from a Branch team member. They were asking me what I had already filled out online. I was confused, but responded. Afterwards, she instructed me to go to the Branch to fund my account. I could not believe it. I opened my account online. Why did I need to go to the Branch to fund it?
After my experience, I learned that this was a usual and standard practice. One hundred percent of our online accounts received a call back. They all were reviewed by a branch team member. They all had to provide answers to questions they had already filled out online.
Friction? This was beyond friction. As the Vice President of Digital Experience, I began researching our online account opening solution. It was a legacy solution, which had not been managed well since its implementation years before; and, it was being administered by the Branch Operations team.
Digital Ownership
As a Digital-forward organization, we moved the ownership of the account opening solution to the digital team and began the analysis of the overall user experience. The team made incremental adjustments, based on the legacy system, but could not make major user-interface changes.
This led to a full vendor search and due diligence process. The goal being to make opening an account as easy and seamless as possible for a potential new member of the credit union, while automating regulatory and fraud procedures.
 If you want to get anything done, you have to be really good at selling the vision.

After reviewing five different vendors, a vendor was selected, contract negotiation occurred and we moved forward with an implementation project.
Deposit Account Opening
We chose to implement a new solution for both online and inbranch. Though the initial focus was online, streamlining the in-branch process would also benefit the member. Through the project, the team focused on mobile-first, opening an account in under three-minutes and automation.
By focusing on mobile-first, we challenged ourselves to keep the form fields to those that are truly relevant to collect and to best practices brought forward by the vendor; rather than introducing fields from the legacy form.
By focusing on opening an account in under three-minutes, we challenged ourselves to consider every time we wanted to add a new field or a new data element, whether or not it had material value, as it added time to collect and impacted the overall member experience.
By focusing on automation, we streamlined the members’ and team members’ experience, taking processes that were previously manual and error-proofing them with system automation.
Success Story
After launching the new account opening solution, we took our in-branch account opening experience from forty-five minutes down to eight minutes. Our online account opening experience, which took up to nine days to have open and fully funded, is now open and fully funded in under seven minutes.
The average opening deposit amount has increased from $252 to $688.
Where previously 100% of online applications were reviewed by a Branch team member, now 35% of applications are automatically approved and booked. This is a value that we will continually work towards improving.
Organizational Change
Change is never easy. Even when providing team members a tool that is easy to use, change itself is difficult. Team members found it difficult to trust that they no longer had to do all of the tasks they previously had to manually complete. It took time for them to trust the system.
They found it nearly unbelievable that they could open a new account so quickly.
Now, they love it. They love how intuitive it is. How easy it is to review the “know your customer” flags and determine if they should or should not open an account. They love the automation.
They are now ready for the next step, business accounts. Which will be our next launch of the new system coming to our branches in late 2026 or early 2027.
Lessons Learned
• If you want to get anything done, you have to be really good at selling the vision. If you cannot explain what you want to do, why you want to do it and the benefit of doing it, you won’t get your initiative off the ground.
• Systems need the right owner and focus. Assigning a branch representative to administer a system, when they need to serve members, will not do the system justice; assign it to a digital or technical representative who can serve the Branches as a Stakeholder.
• Challenge the way things have always been done. Technology no longer changes every 5 years. It is now changing at a revolutionary pace. We need to consider what is available to automate and scale our business.
• Include your stakeholders and their teams, as part of the overall process. This builds buy-in and ownership in the process, project and overall product.
• Include Compliance as a Stakeholder in the project from the beginning, this leads to an overall successful engagement and project.
The articles from these contributors are based on their personal expertise and viewpoints, and do not necessarily reflect the opinions of their employers or affiliated organizations.
EDITOR'S Choice

Fortune Brands Innovations [NYSE: FBIN]
By Juan Guerrero, Director, IT Audit & Data Analytics
The IT Audit Evolution: From Compliance to Strategic Intelligence
Broad River Retail
Wes Dudley, Senior Vice President, Customer Experience
Customer Experience in the Age of Amplified Complexity
Fortune Brands Innovations [NYSE: FBIN]
Scott Barnes, Sr. Director of Enterprise Cyber Security (CISO)
The X-Factor in Cybersecurity: AI and Automation at Work

LHarris Technologies [NYSE: LHX]
Brian Allred, Director of Business Intelligence and Analytics
The Shift from Rigid Dashboards to Conversational Analytics
Ivar's Restaurants
Patrick Yearout, Director of Innovation, Recruitment & Training
From Hiring to Development: Nurturing Teams that Care